CTFS Announces FY2026 Annual Results
- Solid results with resilient growth, capturing new opportunities -
24.09.2026
(24 September 2026, Hong Kong) CTF Services Limited (the “Company” and its subsidiaries, collectively, “CTFS” or the “Group”; Hong Kong stock code: 659) today announced its final results for the year ended 30 June 2026 (“FY2026”).
HIGHLIGHTS
Mr Brian Cheng, Executive Director and Group Co-Chief Executive Officer of CTFS, said, “Market conditions shifted rapidly this year amid external uncertainties and uneven recovery across industries. Against this backdrop, the Group delivered resilient growth and captured new opportunities, achieving strategic expansion in Financial Services and Logistics, which will be important drivers of future growth. Looking ahead, the Group will continue to operate with discipline, recycling capital from mature businesses into higher‑growth sectors, while maintaining a balanced focus on growth, cash flow, and shareholder returns to drive the Group’s continued development. At the same time, Hong Kong’s first Five‑Year Plan is expected to create meaningful opportunities. We are fully committed to supporting and contributing to Hong Kong’s future development and seizing growth opportunities to deliver value for our shareholders.”
Mr Gilbert Ho, Executive Director and Group Co-Chief Executive Officer of CTFS, added, “Our diversified business portfolio, spanning industries across different economic cycles, provides a solid foundation for stable cash flow generation. Supported by prudent financial management and an experienced management team, we are well-positioned to navigate risks and maintain ample liquidity in a changing market environment. Going forward, we will further strengthen our portfolio through strategic capital allocation and robust risk management, ensuring sustainable long‑term value creation for shareholders.”
Healthy Capital Structure
During FY2026, the Group demonstrated balance sheet resilience and disciplined financial management, maintaining stable borrowing costs at approximately 4.1% per annum (FY2025: approximately 4.1%) despite a dynamic interest rate environment, while optimizing its debt mix and risk profile to achieve a desirable capital structure. During the year, in view of the expected appreciation of Renminbi (“RMB”) against the Hong Kong dollar, The Group proactively reduced its RMB borrowings used as a natural hedge against RMB-denominated assets. As at 30 June 2026, the Group’s net gearing ratio decreased to 28%1 from 37% as at 30 June 2025, reinforcing the Group’s capacity to pursue future growth opportunities while maintaining financial resilience.
1 The 0.75% Exchangeable Bonds, which are accounted for as financial liabilities at fair value through profit or loss, are excluded from both the Net Debt and Net Gearing Ratio calculations. If the 0.75% Exchangeable Bonds were included as debt, the net gearing ratio would be 33% as at 30 June 2026.
Optimization of Businesses
The Group advanced with its portfolio optimization strategy, recycling capital from mature, traditional infrastructure assets into businesses with better long-term growth prospects, higher scalability and greater recurring income potential.
Projects undertaken in FY2026:
Strategic expansions:
Financial Services:
Logistics:
Strategic Investments:
Divestment:
Projects signed in FY2027 (completed or pending completion after 30 June 2026):
Logistics:
Business Performance Highlights
Financial Services
Strong AOP and CSM release growth momentum
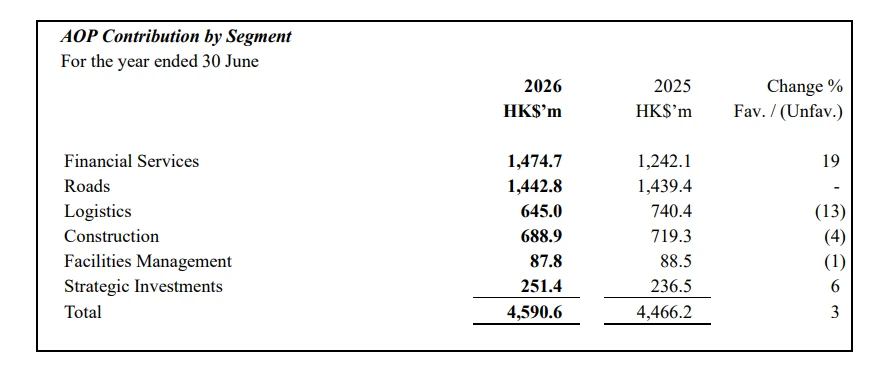
In FY2026, the Financial Services segment became the Group’s largest AOP contributor. AOP rose by 19% to HK$1,474.7 million. This was primarily driven by higher Contractual Service Margin (“CSM”) release from Chow Tai Fook Life Insurance Company Limited (“CTF Life”), which rose 21% year-on-year to HK$1,368 million. Annual Premium Equivalent (“APE”) grew by 7% year-on-year to HK$3,540 million, while new business premium increased by 74% year-on year to HK$9,333 million. The strong new business premium growth provided the foundation for the Value of New Business (“VONB”), which increased by 30% year-on-year to HK$1,308 million. With this momentum, VONB margin expanded to 37% in FY2026 (FY2025: 30%).
Growth was supported by the ongoing enhancement of CTF Life’s diversified distribution platform. The agency channel delivered robust performance, with APE rising 10% year-on-year to HK$1,106 million and new business premium increasing 85% year-on-year to HK$2,945 million. New business premium growth significantly outpaced the 6% increase in agency headcount to over 2,200 agents as at 30 June 2026. This drove a 73% year-on-year improvement in agency productivity in terms of new business premium. This was further reflected in a 29% year-on-year increase in Million Dollar Round Table (“MDRT”) registered members as at 31 December 2025, underscoring the growing professionalism and effectiveness of the agency model.
The partnership channel also gained momentum, with APE rising by 16% year-on-year to HK$2,241 million and new business premium surging by 138% year-to-year to HK$5,135 million.
CTF Life also maintained a robust financial position. As at 30 June 2026, its solvency ratio under the Hong Kong Risk Based Capital regime further edged up to 285% (30 June 2025: 279%), which is almost three times the minimum regulatory requirement at 100%. Embedded value grew by 12% year-on-year to HK$28.4 billion, driven by expected return on existing business, new business growth and favourable market performance.
Following completion of the investment in uSMART in November 2025, the Group holds a 13.05% equity interest in uSMART, which contributed positively to the Group’s AOP in FY2026. Its revenue increased approximately fourfold year‑on‑year.
Roads
Stable performance amid ongoing external headwinds
In FY2026, the Roads segment reported AOP of HK$1,442.8 million, remaining broadly flat year-on-year. On a like-for-like basis, average daily traffic flow and toll revenue declined by approximately 1% year-on-year, mainly due to partial closures arising from temporary traffic disruptions on the Beijing-Zhuhai Expressway (Guangzhou-Zhuhai Section) and Guangzhou-Zhaoqing Expressway during their ongoing expansion works. As at 30 June 2026, the toll road portfolio had an average remaining concession period of approximately 11 years.
To advance its portfolio and in line with the Group’s business optimization strategy, the Group announced in May 2026 the disposal of its entire interest in the Hunan Changliu Expressway with the transaction completed in July 2026.
Logistics
Diversified logistics investments
The Logistics segment reported AOP of HK$645.0 million for FY2026, representing a decrease of 13% year-on-year. Excluding the impact from deferred tax provisions for the logistics properties in the Chinese Mainland, AOP declined 10% year-on-year. Continued growth in contributions from China United International Rail Containers Co., Limited (“CUIRC”) helped mitigate the lower earnings from ATL Logistics Centre Hong Kong Limited (“ATL”) in Hong Kong.
As at 30 June 2026, ATL’s occupancy rate rebounded sharply to 84.5% (30 June 2025: 80.7%) from 75.2% as at 31 December 2025. While the average occupancy rate across the seven logistics assets in Chengdu, Wuhan and Suzhou was 86.3% as at 30 June 2026 (30 June 2025: 87.5%).
During FY2026, the Group further expanded its logistics asset footprint and strengthened portfolio synergies across the Chinese Mainland through the acquisition of four logistics properties in Dongguan, Shanghai, Ningbo and Changzhou. Following the acquisitions, the Group’s logistics portfolio in the Chinese Mainland comprised eleven assets, with an overall average occupancy rate of 86.2% as at 30 June 2026. Excluding the impact from deferred tax, AOP from logistics properties in the Chinese Mainland recorded a 11% growth year-on-year in FY2026, reflecting the immediate AOP contribution from newly acquired logistics assets.
In FY2026, AOP of CUIRC increased by 2% year-on-year, while throughput rose by 8% year-on-year to 7,564,000 TEUs, driven by growing demand for rail freight services, ancillary logistics services, and higher terminal handling volumes.
Construction
Delivering long‑term value through proven construction expertise
CTFS Construction Group comprises four established operating entities with complementary specialist capabilities: Hip Hing Group, Vibro Group, Quon Hing Group, and Hsin Chong Aster. Together, these entities enable us to serve public-sector, institutional and private-sector clients across key stages of the construction value chain. As at 30 June 2026, newly secured contracts with aggregate value of approximately HK$16.9 billion, the gross value of contracts on hand increased by 7% year-on-year to HK$62.7 billion. Remaining works to be completed stood at a healthy HK$34.9 billion.
Major contracts awarded during the financial year included design and build of a joint user complex and public open space at Cheung Sha Wan Road in Sham Shui Po, the construction of a public housing development at Yip On Factory Estate, the management contract for maintenance and completion works for the subsidized sale flats development at Anderson Road Quarry Site R2-2, and the main contract for Pak Shing Kok ventilation building property development at Chiu Shun Road, Tseung Kwan O Town Lot No.132.
While CTFS Construction Group strengthened its order book and project mix, profitability was affected by project margin pressure during FY2026, AOP decreased modestly by 4% to HK$688.9 million.
Facilities Management
Manage iconic Hong Kong venues to capture long-term growth
In FY2026, segment AOP decreased by 1% year-on-year to HK$87.8 million. Gleneagles Hospital Hong Kong (“GHK”) recorded significant growth in AOP, helped mitigate the impact of a lower contribution from Hong Kong Convention and Exhibition Centre (“HKCEC”), reflecting higher depreciation and capital expenditure, as well as the Attributable Operating Loss (“AOL”) recorded by Kai Tak Sports Park Limited (“KTSPL”), in which the Group holds a 25% interest, during the ramp-up phase of Kai Tak Sports Park.
At the Hong Kong Convention and Exhibition Centre, the continued recovery in business travel and MICE activities drove higher exhibition and conference rental income and increased food and beverage revenue amid HKCEC’s enhanced marketing and business development initiatives. During FY2026, total attendance of HKCEC reached approximately 7.7 million across 786 events, broadly in line with prior year.
Gleneagles Hospital Hong Kong became a key growth driver for the Facilities Management segment during FY2026. Revenue maintained its upward trajectory, while EBITDA increased strongly by 15% year-on-year. AOP contribution to the Group surged more than fourfold. The number of inpatients, outpatients and day cases rising by 3%, 1% and 9%, respectively.
GHK further expanded its healthcare ecosystem and outpatient network, including launch of Gleneagles PharmaHome, a digital pharmacy offering online purchasing and home delivery services to enhance patient convenience. In parallel, Parkway Medical Services (Hong Kong) Limited, a business venture between IHH Healthcare Berhad and the Group, also strengthened GHK’s integrated network, as Gleneagles MediCentre in Admiralty commenced operations in October 2025, brining GHK’s clinic network and healthcare facilities to seven clinics and one laboratory.
Kai Tak Sports Park had attracted over 20 million visits between its official opening in March 2025 to 30 June 2026, hosted nearly 150 major sports and entertainment events and facilitated more than 250 days of sporting activities. Utilization rates at Kai Tak Stadium and Kai Tak Arena achieved close to 90%, underscoring strong demand and the growing appeal of the precinct. Kai Tak Mall also delivered encouraging results, benefiting from strong visitor traffic and retail-event synergies, with occupancy reaching approximately 87% as at 30 June 2026 (30 June 2025: approximately 80%).
Outlook
The Group will leverage its diversified business portfolio, operational expertise and disciplined capital allocation to navigate evolving market conditions and capture opportunities arising from long-term structural growth trends. It will further optimize its portfolio by recycling capital from mature businesses into higher‑growth and more scalable sectors, especially in Financial Services and Logistics.
Meanwhile, the Group will continue to maintain a disciplined approach to capital deployment and investment selection, while remaining committed to creating sustainable long‑term value for stakeholders.
HIGHLIGHTS
- The profit attributable to shareholders of the Company increased by 11% year-on-year to HK$2,392.6 million.
- The Group’s overall Attributable Operating Profit (AOP) grew by 3% year-on-year to HK$4,590.6 million.
- The Group’s financial position remained solid. Total available liquidity stood at approximately HK$31.3 billion as at 30 June 2026, comprising cash and bank balances of approximately HK$20.8 billion and unutilized committed banking facilities of approximately HK$10.5 billion.
- Prudent and proactive balance sheet management. As at 30 June 2026, Net Debt decreased by 20% year-on year to HK$11.7 billion, and Net Gearing Ratio reduced to 28% from 37% as at 30 June 2025.
- FY2026 final ordinary dividend and total ordinary dividends:
- Proposed final ordinary dividend for FY2026 is HK$0.33 per share, representing an approximately 4% year-on-year increase on a comparable basis after adjusting the FY2025 final ordinary dividend per share to reflect the enlarged share capital base following the 1-for-10 bonus issue in December 2025.
- Together with the interim ordinary dividend of HK$0.28 per share, total ordinary dividends for FY2026 will be HK$0.61 per share.
- The total ordinary dividends amount will be increased by approximately 6 % year-on-year to HK$2.8 billion, reflecting the Group’s commitment to a sustainable and progressive dividend policy.
- The Board has proposed a bonus issue of shares on the basis of one bonus share for every Ten existing shares held by the Shareholders to recognize shareholder’s support and enhance share liquidity.
Mr Brian Cheng, Executive Director and Group Co-Chief Executive Officer of CTFS, said, “Market conditions shifted rapidly this year amid external uncertainties and uneven recovery across industries. Against this backdrop, the Group delivered resilient growth and captured new opportunities, achieving strategic expansion in Financial Services and Logistics, which will be important drivers of future growth. Looking ahead, the Group will continue to operate with discipline, recycling capital from mature businesses into higher‑growth sectors, while maintaining a balanced focus on growth, cash flow, and shareholder returns to drive the Group’s continued development. At the same time, Hong Kong’s first Five‑Year Plan is expected to create meaningful opportunities. We are fully committed to supporting and contributing to Hong Kong’s future development and seizing growth opportunities to deliver value for our shareholders.”
Mr Gilbert Ho, Executive Director and Group Co-Chief Executive Officer of CTFS, added, “Our diversified business portfolio, spanning industries across different economic cycles, provides a solid foundation for stable cash flow generation. Supported by prudent financial management and an experienced management team, we are well-positioned to navigate risks and maintain ample liquidity in a changing market environment. Going forward, we will further strengthen our portfolio through strategic capital allocation and robust risk management, ensuring sustainable long‑term value creation for shareholders.”
Healthy Capital Structure
During FY2026, the Group demonstrated balance sheet resilience and disciplined financial management, maintaining stable borrowing costs at approximately 4.1% per annum (FY2025: approximately 4.1%) despite a dynamic interest rate environment, while optimizing its debt mix and risk profile to achieve a desirable capital structure. During the year, in view of the expected appreciation of Renminbi (“RMB”) against the Hong Kong dollar, The Group proactively reduced its RMB borrowings used as a natural hedge against RMB-denominated assets. As at 30 June 2026, the Group’s net gearing ratio decreased to 28%1 from 37% as at 30 June 2025, reinforcing the Group’s capacity to pursue future growth opportunities while maintaining financial resilience.
1 The 0.75% Exchangeable Bonds, which are accounted for as financial liabilities at fair value through profit or loss, are excluded from both the Net Debt and Net Gearing Ratio calculations. If the 0.75% Exchangeable Bonds were included as debt, the net gearing ratio would be 33% as at 30 June 2026.
Optimization of Businesses
The Group advanced with its portfolio optimization strategy, recycling capital from mature, traditional infrastructure assets into businesses with better long-term growth prospects, higher scalability and greater recurring income potential.
Projects undertaken in FY2026:
Strategic expansions:
Financial Services:
- Acquisition of 13.05% stake in uSmart Inlet Group Limited (“uSMART”), a leading technology-driven financial services company (Completed in Nov 2025)
- Acquisition of 65% equity interest in Blackhorn Group Limited, an external asset manager (Completed in Jul 2026)
Logistics:
- Investments in an artificial intelligence data centre (“AIDC”) in Jiangsu Province (Completed in Nov 2025)
- Acquisition of a logistics property in the Greater Bay Area (Completed in Dec 2025)
- Acquisition of three logistics properties in the Yangtze River Delta (Completed in Jan 2026)
Strategic Investments:
- Investments in Battery Energy Storage System (BESS) projects in Iisalmi and Petäjävesi in Finland (Completed in Apr 2026)
Divestment:
- To monetize its approximately 10% stake in Shoucheng through the issuance of 0.75% Exchangeable Bonds with an aggregate principal amount of HK$2,218 million (Completed in Oct 2025)
- Divestment of entire interests in Hunan Changliu Expressway (Completed in Jul 2026)
Projects signed in FY2027 (completed or pending completion after 30 June 2026):
Logistics:
- Acquisition of a logistic property in Yangtze River Delta
- Acquisition of a 70% equity interest in AIDC project in Hebei Province
- Acquisition of a 40% equity interest in an AIDC project in Malaysia
Business Performance Highlights
Financial Services
Strong AOP and CSM release growth momentum
In FY2026, the Financial Services segment became the Group’s largest AOP contributor. AOP rose by 19% to HK$1,474.7 million. This was primarily driven by higher Contractual Service Margin (“CSM”) release from Chow Tai Fook Life Insurance Company Limited (“CTF Life”), which rose 21% year-on-year to HK$1,368 million. Annual Premium Equivalent (“APE”) grew by 7% year-on-year to HK$3,540 million, while new business premium increased by 74% year-on year to HK$9,333 million. The strong new business premium growth provided the foundation for the Value of New Business (“VONB”), which increased by 30% year-on-year to HK$1,308 million. With this momentum, VONB margin expanded to 37% in FY2026 (FY2025: 30%).
Growth was supported by the ongoing enhancement of CTF Life’s diversified distribution platform. The agency channel delivered robust performance, with APE rising 10% year-on-year to HK$1,106 million and new business premium increasing 85% year-on-year to HK$2,945 million. New business premium growth significantly outpaced the 6% increase in agency headcount to over 2,200 agents as at 30 June 2026. This drove a 73% year-on-year improvement in agency productivity in terms of new business premium. This was further reflected in a 29% year-on-year increase in Million Dollar Round Table (“MDRT”) registered members as at 31 December 2025, underscoring the growing professionalism and effectiveness of the agency model.
The partnership channel also gained momentum, with APE rising by 16% year-on-year to HK$2,241 million and new business premium surging by 138% year-to-year to HK$5,135 million.
CTF Life also maintained a robust financial position. As at 30 June 2026, its solvency ratio under the Hong Kong Risk Based Capital regime further edged up to 285% (30 June 2025: 279%), which is almost three times the minimum regulatory requirement at 100%. Embedded value grew by 12% year-on-year to HK$28.4 billion, driven by expected return on existing business, new business growth and favourable market performance.
Following completion of the investment in uSMART in November 2025, the Group holds a 13.05% equity interest in uSMART, which contributed positively to the Group’s AOP in FY2026. Its revenue increased approximately fourfold year‑on‑year.
Roads
Stable performance amid ongoing external headwinds
In FY2026, the Roads segment reported AOP of HK$1,442.8 million, remaining broadly flat year-on-year. On a like-for-like basis, average daily traffic flow and toll revenue declined by approximately 1% year-on-year, mainly due to partial closures arising from temporary traffic disruptions on the Beijing-Zhuhai Expressway (Guangzhou-Zhuhai Section) and Guangzhou-Zhaoqing Expressway during their ongoing expansion works. As at 30 June 2026, the toll road portfolio had an average remaining concession period of approximately 11 years.
To advance its portfolio and in line with the Group’s business optimization strategy, the Group announced in May 2026 the disposal of its entire interest in the Hunan Changliu Expressway with the transaction completed in July 2026.
Logistics
Diversified logistics investments
The Logistics segment reported AOP of HK$645.0 million for FY2026, representing a decrease of 13% year-on-year. Excluding the impact from deferred tax provisions for the logistics properties in the Chinese Mainland, AOP declined 10% year-on-year. Continued growth in contributions from China United International Rail Containers Co., Limited (“CUIRC”) helped mitigate the lower earnings from ATL Logistics Centre Hong Kong Limited (“ATL”) in Hong Kong.
As at 30 June 2026, ATL’s occupancy rate rebounded sharply to 84.5% (30 June 2025: 80.7%) from 75.2% as at 31 December 2025. While the average occupancy rate across the seven logistics assets in Chengdu, Wuhan and Suzhou was 86.3% as at 30 June 2026 (30 June 2025: 87.5%).
During FY2026, the Group further expanded its logistics asset footprint and strengthened portfolio synergies across the Chinese Mainland through the acquisition of four logistics properties in Dongguan, Shanghai, Ningbo and Changzhou. Following the acquisitions, the Group’s logistics portfolio in the Chinese Mainland comprised eleven assets, with an overall average occupancy rate of 86.2% as at 30 June 2026. Excluding the impact from deferred tax, AOP from logistics properties in the Chinese Mainland recorded a 11% growth year-on-year in FY2026, reflecting the immediate AOP contribution from newly acquired logistics assets.
In FY2026, AOP of CUIRC increased by 2% year-on-year, while throughput rose by 8% year-on-year to 7,564,000 TEUs, driven by growing demand for rail freight services, ancillary logistics services, and higher terminal handling volumes.
Construction
Delivering long‑term value through proven construction expertise
CTFS Construction Group comprises four established operating entities with complementary specialist capabilities: Hip Hing Group, Vibro Group, Quon Hing Group, and Hsin Chong Aster. Together, these entities enable us to serve public-sector, institutional and private-sector clients across key stages of the construction value chain. As at 30 June 2026, newly secured contracts with aggregate value of approximately HK$16.9 billion, the gross value of contracts on hand increased by 7% year-on-year to HK$62.7 billion. Remaining works to be completed stood at a healthy HK$34.9 billion.
Major contracts awarded during the financial year included design and build of a joint user complex and public open space at Cheung Sha Wan Road in Sham Shui Po, the construction of a public housing development at Yip On Factory Estate, the management contract for maintenance and completion works for the subsidized sale flats development at Anderson Road Quarry Site R2-2, and the main contract for Pak Shing Kok ventilation building property development at Chiu Shun Road, Tseung Kwan O Town Lot No.132.
While CTFS Construction Group strengthened its order book and project mix, profitability was affected by project margin pressure during FY2026, AOP decreased modestly by 4% to HK$688.9 million.
Facilities Management
Manage iconic Hong Kong venues to capture long-term growth
In FY2026, segment AOP decreased by 1% year-on-year to HK$87.8 million. Gleneagles Hospital Hong Kong (“GHK”) recorded significant growth in AOP, helped mitigate the impact of a lower contribution from Hong Kong Convention and Exhibition Centre (“HKCEC”), reflecting higher depreciation and capital expenditure, as well as the Attributable Operating Loss (“AOL”) recorded by Kai Tak Sports Park Limited (“KTSPL”), in which the Group holds a 25% interest, during the ramp-up phase of Kai Tak Sports Park.
At the Hong Kong Convention and Exhibition Centre, the continued recovery in business travel and MICE activities drove higher exhibition and conference rental income and increased food and beverage revenue amid HKCEC’s enhanced marketing and business development initiatives. During FY2026, total attendance of HKCEC reached approximately 7.7 million across 786 events, broadly in line with prior year.
Gleneagles Hospital Hong Kong became a key growth driver for the Facilities Management segment during FY2026. Revenue maintained its upward trajectory, while EBITDA increased strongly by 15% year-on-year. AOP contribution to the Group surged more than fourfold. The number of inpatients, outpatients and day cases rising by 3%, 1% and 9%, respectively.
GHK further expanded its healthcare ecosystem and outpatient network, including launch of Gleneagles PharmaHome, a digital pharmacy offering online purchasing and home delivery services to enhance patient convenience. In parallel, Parkway Medical Services (Hong Kong) Limited, a business venture between IHH Healthcare Berhad and the Group, also strengthened GHK’s integrated network, as Gleneagles MediCentre in Admiralty commenced operations in October 2025, brining GHK’s clinic network and healthcare facilities to seven clinics and one laboratory.
Kai Tak Sports Park had attracted over 20 million visits between its official opening in March 2025 to 30 June 2026, hosted nearly 150 major sports and entertainment events and facilitated more than 250 days of sporting activities. Utilization rates at Kai Tak Stadium and Kai Tak Arena achieved close to 90%, underscoring strong demand and the growing appeal of the precinct. Kai Tak Mall also delivered encouraging results, benefiting from strong visitor traffic and retail-event synergies, with occupancy reaching approximately 87% as at 30 June 2026 (30 June 2025: approximately 80%).
Outlook
The Group will leverage its diversified business portfolio, operational expertise and disciplined capital allocation to navigate evolving market conditions and capture opportunities arising from long-term structural growth trends. It will further optimize its portfolio by recycling capital from mature businesses into higher‑growth and more scalable sectors, especially in Financial Services and Logistics.
Meanwhile, the Group will continue to maintain a disciplined approach to capital deployment and investment selection, while remaining committed to creating sustainable long‑term value for stakeholders.
PDF
